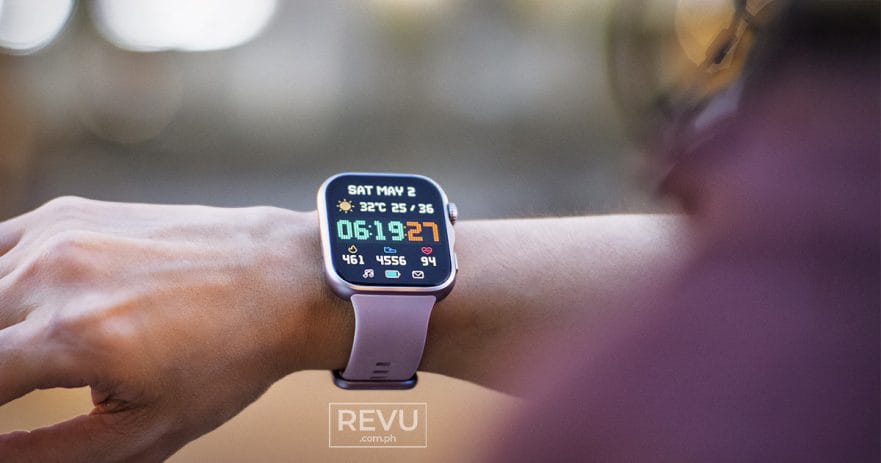
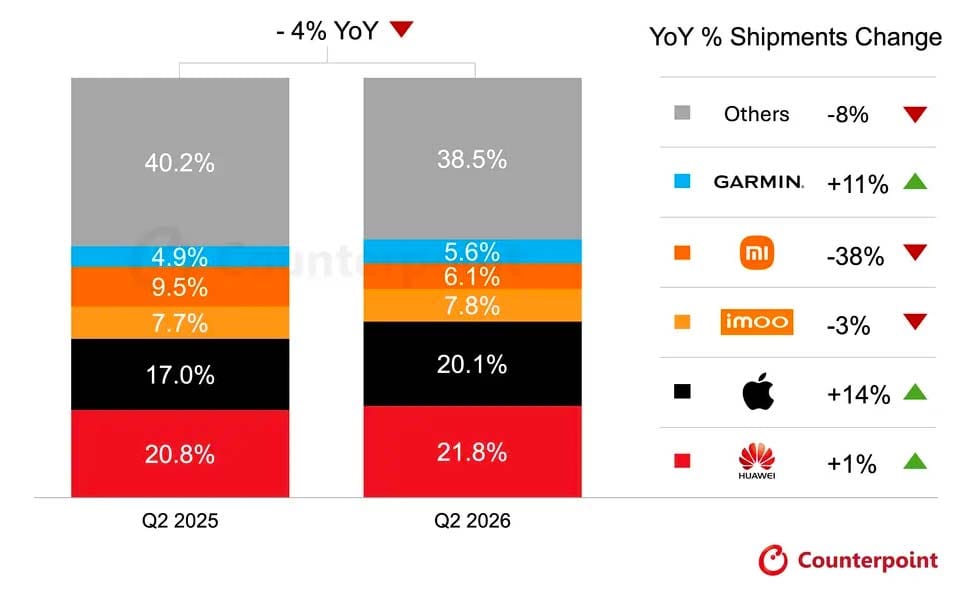
The global smartwatch market has hit a wall. Worldwide shipments fell 4% in the second quarter of 2026, marking the first year-over-year decline in a year and suggesting that consumers are becoming reluctant to upgrade for yet another collection of incremental wrist-tech improvements.
According to the latest data from Counterpoint Research, premium smartwatch owners are holding onto their devices longer, waiting for a truly compelling reason to upgrade. At the budget end of the spectrum, cheap, basic trackers are steadily losing ground. The result is an industry caught between cautious consumers and increasingly sophisticated hardware that isn’t giving them enough reasons to open their wallets.
Beneath the broader slowdown, however, another battle is getting much more interesting: HUAWEI and Apple are now separated by barely more than a percentage point.
HUAWEI held onto the No. 1 position with a record 21.8% share of the global market, despite only 1% year-over-year growth. That lead is heavily dependent on its home turf, with roughly 80% of the technology giant’s shipments coming strictly from China.
Apple, meanwhile, is closing the gap at a much faster pace. The Cupertino company captured 20.1% of the market and posted 14% year-over-year growth — the fastest rate among the top five smartwatch brands.
And Apple didn’t get there by pushing consumers toward its most expensive, titanium-clad models. Instead, the mainstream Apple Watch Series 11 and the budget-friendly Apple Watch SE 3 accounted for more than 80% of its total Q2 shipments. That is a telling shift. Consumers appear willing to pay for reliability, core health features, and seamless ecosystem integration, but they are not necessarily willing to pay an ultra-premium tax for them.
The rest of the top five paints an equally revealing picture. Imoo held third place with a 7.8% market share despite a 3% decline in shipments. Xiaomi suffered a much steeper setback, with shipments plunging 38% year over year and its market share falling to 6.1%, good enough for fourth place. Garmin went in the opposite direction. The fitness-focused brand grew 11% to claim fifth place with a 5.6% share, reinforcing the value of having a clearly defined audience. Serious athletes and outdoor enthusiasts, it seems, still have reasons to spend premium money on specialized, rugged hardware.
For everyone else, the upgrade equation is getting harder. Why spend $399 (around ₱25,000) or more on a new flagship smartwatch when a two-year-old model still counts your steps, tracks your sleep, monitors your health metrics, and delivers notifications perfectly well?
Counterpoint expects the global smartwatch market to eke out just 1% growth for all of 2026. But that doesn’t mean the industry is doomed; it just means the market is in a holding pattern. Once manufacturers can flawlessly integrate edge AI, reliable blood pressure tracking, and the holy grail of wearables — non-invasive blood glucose monitoring — that stagnant replacement cycle is going to snap. Until then, the industry is just playing a high-stakes waiting game.
Learn About This Author